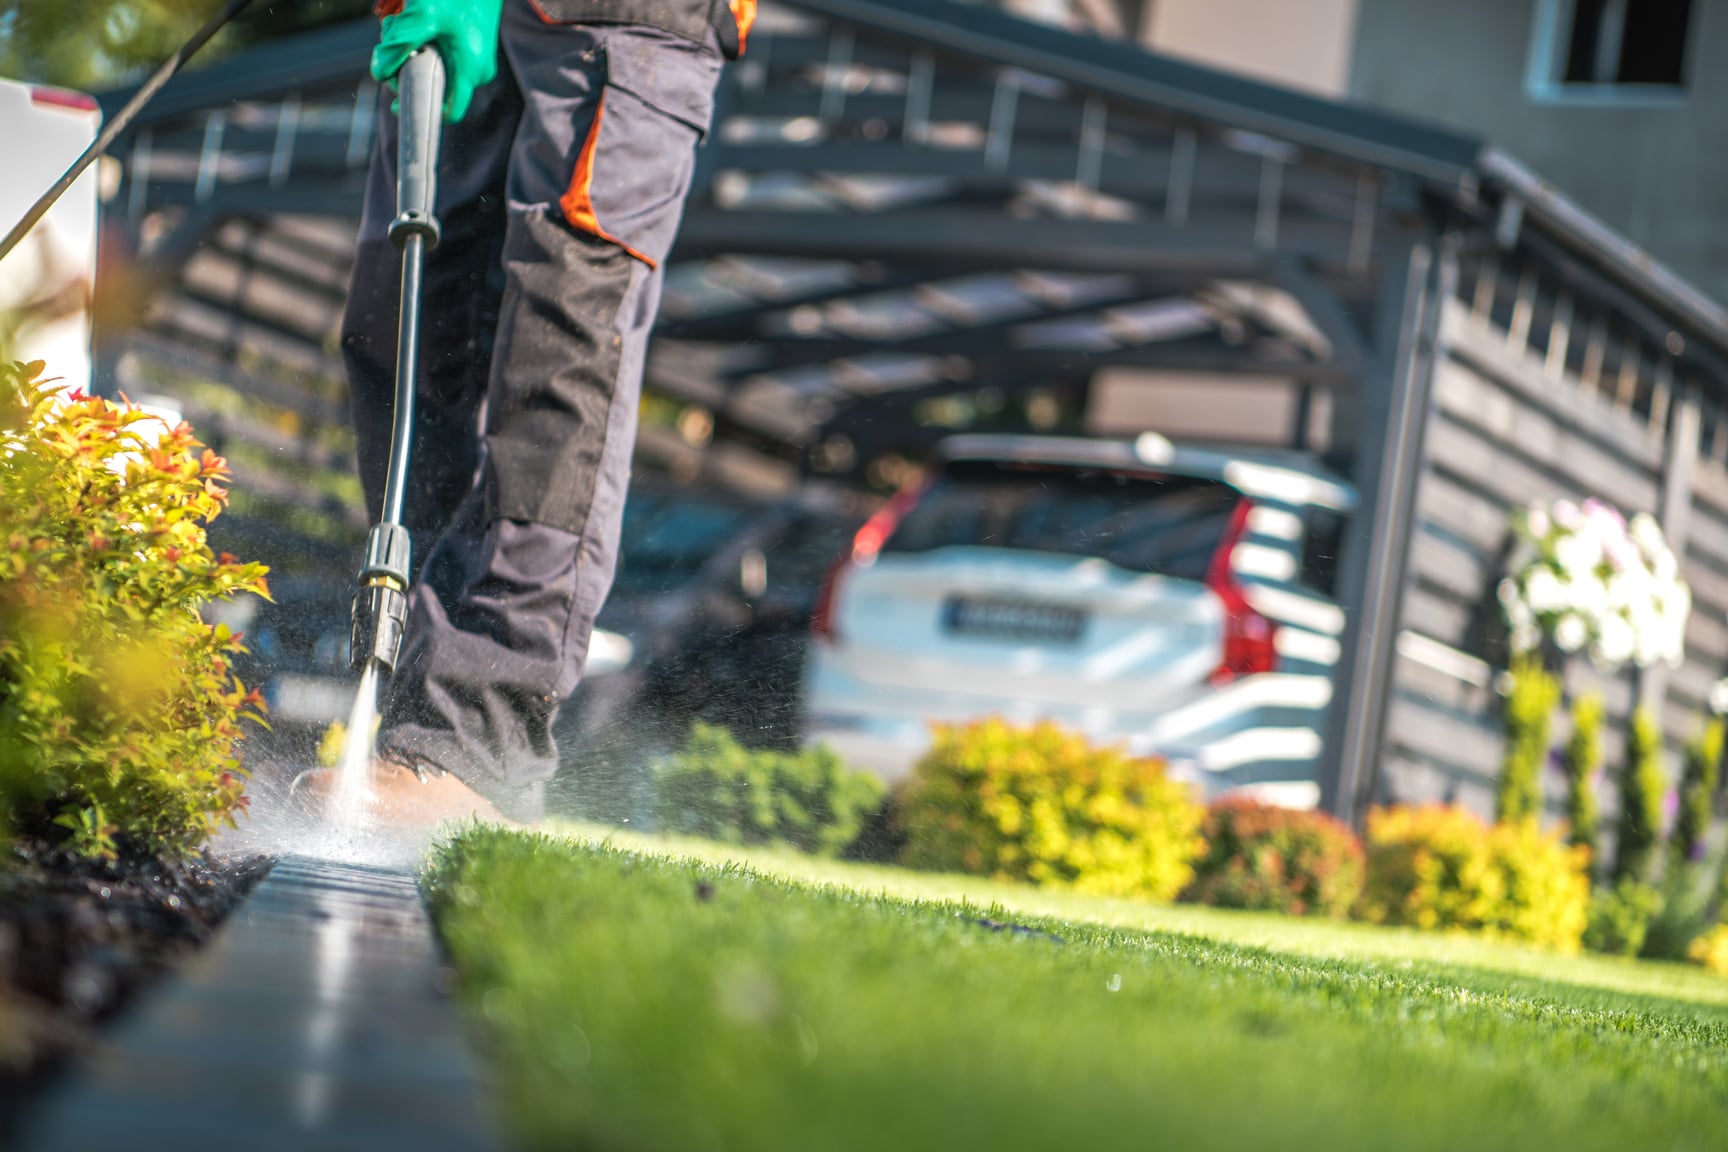
When the surface you wash is the claim
The defining exposure in this trade is damage to the property you were hired to clean. It is the loss this page keeps
returning to, because it is where the wording of a general liability policy matters most.
Striping and etching
A surface cleaner held too long in place, a tip too close to soft concrete, or a pass at the wrong pressure leaves
stripes, lap marks or an etched finish that a second wash will not remove. On a wood deck the same mistake raises
the grain and furs the boards. The customer sees it the moment the surface dries.
Window seals, glass and screens
Water driven at the edge of a window can break the seal on insulated glass and leave fog between the panes weeks
later, long after the invoice is paid. Screens tear, weep holes clog and caulk lifts. A complaint that arrives long
after the wash still traces back to it.
Oxidation, paint and finishes
Chalky, oxidized siding and older paint come off unevenly under pressure or under the wrong solution, leaving
streaks and bare patches that read as damage rather than dirt. Aluminum trim, light fixtures and the finish on a
car parked nearby can spot or dull when a mix lands on them and dries in the sun.
Water where it should not go
Water forced behind siding, under flashing, past a garage door seal or into an outdoor outlet turns into a mold,
rot or electrical complaint. On a roof, the wrong technique strips granules and pushes water under the shingles.
These losses surface inside walls and ceilings, out of sight until they are expensive to open up.
The care, custody or control question
A standard commercial general liability policy pays for property damage your work causes to others, then excludes
the kinds of property that sit closest to that work. It excludes personal property in your care, custody or
control. It excludes that particular part of real property on which you are performing operations, when the damage
arises out of those operations, and that particular part of any property that must be restored, repaired or
replaced because your work was incorrectly performed on it. Read together, those exclusions can leave the driveway
you were washing, at the moment you were washing it, outside the policy.
So the question to put to any quote is precise: how does this policy handle damage to the surface I am working on?
Some insurers write the standard exclusions as they stand. Some add endorsements that narrow coverage further for
contractors who clean. Some offer an endorsement that gives back a measure of coverage for property in your care,
custody or control, with its own limit and deductible. Ask which applies, ask to read the wording, and compare it
before you compare premiums. When you ask us for a quote, ask us that question too; the answer belongs beside the
price.